When disaster hits, data isn't enough
Jeremy Greenberg shares what insurers can learn from FEMA about disaster response, turning data into decisions, and preparing teams before catastrophe strikes.
“Do the basics brilliantly. Every disaster, whether it was the most unique disaster I ever responded to, you go back to the basics, you assess the situation, make a determination on what the resources are, and you work your way through a progression of steps to bring stability to that incident.”
Jeremy GreenbergPresident of Provincial Strategies LLCEpisode 2 transcript
[00:00:00] David Tobias: Hello and welcome to the Reality Layer podcast. I’m Dave Tobias, Chief product officer at Nearmap. Let’s get into today’s episode. Today I’m joined by Jeremy Greenberg, an emergency and risk management leader with over two decades of federal service to his name. Jeremy spent years at FEMA helping coordinate the response to hundreds of presidentially declared disasters, from hurricanes to wildfires and cyber incidents to terrorist attacks. Today, he advises organizations on emergency preparedness risks and what they need to do to be prepared for these situations. In this episode, we’ll explore how disaster response is changing, why faster and better data matters in the first hours of events, and what insurers can learn from the way that emergency managers prepare, coordinate and respond to events. Welcome Jeremy, you thank Dave.
[00:00:53] Jeremy Greenberg: Thank you so much for having me today. I’m excited to have the chat.
[00:00:56] David Tobias: Jeremy, you’ve spent a large part of your career working in environments where decisions have to be made quickly, the stakes are exceedingly high. What drew you to this kind of high pressure work?
[00:01:08] Jeremy Greenberg: It’s a great question. I can’t map it back to, you know, one specific thing. You don’t, you’re not in elementary school and go, oh, I want to be an emergency manager. It just wasn’t a profession, it wasn’t a thing that I knew about. But I did join the volunteer ambulance company when I was 16 years old and mainly because my parents wouldn’t let me join the fire department. You had to be 18 and started riding a fire or ambulances. And then I did join the fire department and just was drawn to really being in the space where you can try and help a situation, help a person. I often joke that I played a lot of sports but wasn’t good. So the next best thing was you join the fire department. And I had a blast. And then from there I really have had a series of great opportunities. I went to went to College in Washington D.C. where seat of government so internships were easy to come by. Got a cool job as an intern at the Department of Justice and then sort of moved throughout my career in different departments and agencies and really kept angling towards this emergency management space and had the as a local responder had the chance to respond to the Pentagon on 911 and literally be a part of every disaster that we’ve had in the US since then in a variety of different ways. And really just having awesome colleagues and great mentors sort of just kept progressing me through the emergency management space to ultimately the job that I knew that I wanted, which was the director response operations over at FEMA and had the chance to be the deputy director there and then director for about five years and it was just, it was fantastic and really a phenomenal team.
[00:02:43] David Tobias: So you linked emergency and management to wedding and fraternity party planning. For me, what can what planning a wedding or a fraternity party teach you about emergency response and emergency management?
[00:02:57] Jeremy Greenberg: I think this holds true for any sort of risk proposition. Right. Everybody just by nature, you don’t want to, you don’t want to think about your risk, your own vulnerabilities. I’m not talking about the emotional side, I’m just talking about like a physical risk, you know, that won’t happen to me. And there’s, there’s a ton, ton of material research out there that says if you empower someone, they are much more likely to survive a problem set. It’s why when you get on an airplane, no matter how many times you fly, they specifically say even if you’re a frequent flyer, please pay attention and listen to me as every aircraft is different.
[00:03:26] David Tobias: Right?
[00:03:26] Jeremy Greenberg: You’ve, you’ve heard that and not everybody does it, but it is, there’s a value proposition in there of if you empower someone they’re going to be able to survive a little better. And I from using that as a leap off point. That’s why when you talk about incident command or emergency management, prioritization or resource allocation, not that they’re buzzwordy or technical, people are like what are you talking about? I don’t want to listen to you. You know, you go to a private sector company, an insurance company, you say hey, I’m going to build you this ICS structure to respond. They say no, we don’t do those things. So early on in my career when I started becoming an instructor, both on the fireside and on the, on the emergency preparedness side, I wanted to think of things that were simple, that we’ve all done. Not that a wedding is simple, discount that, but you know, something that people can associate with. And even when you say you a smile on your face, a fraternity party, a wedding, you think about these things in practical terms. There’s an easy overlay to an operations section, logistics section, an admin, finance section, right. As a commander, whether it’s the bride or the host of the fraternity, so using common terms and common activities that people have all generally had fond memories of, to talk about something that’s high risk generally leads to a better outcome.
[00:04:40] David Tobias: How has that changed the way orgs need to think about managing these events? Right. Whether you’re an insurer or a federal or state, you know, city agency, how do you have to change? Because the predictability seems to have changed.
[00:04:54] Jeremy Greenberg: I completely agree just by stats that disaster types, natural disasters are increasing in frequency and intensity. And to your point about geolocations, a couple years ago, maybe four or five years ago, and there was a tornado in December in New Jersey. And I remember I was at FEMA at the time and the assistant administrator for response to recovery senior person, I was running up, she looked over at me, she said, hey, how often does this happen? And trying to not raise any concerns, you know, fairly often. And they didn’t know if she was asking about a tornado in New Jersey, a tornado in December. But my answer was wrong for both of them.
[00:05:28] David Tobias: Right?
[00:05:28] Jeremy Greenberg: Like it at the time, it didn’t happen that frequently. But from an organizational perspective, whether you’re a public sector entity or a private sector entity, I think there are a couple things that you need to take into consideration. One, and we’ve chatted about this just over time, is knowing that you need to invest in your team. The ability to train and prepare is a critical aspect of anything you do. To your point, that’s not true anymore. So with this, this constant tail of one disaster being the head of another disaster, geographic dispersity, things that we knew to be true just aren’t anymore. I think focusing on training cycles, preparedness cycles, and being able to search your individuals, search your teams into places that maybe you didn’t normally have to do it. The tornado in New Jersey will always be that reminder for me. If you say, hey, there’s a tornado warning in the Midwest, people know how to react. It’s much like if you have snow in the Northeast, people know how to react. But when you have, you know, freezing rain and ice in Atlanta, that’s not what people are programmed for. They’re not used to those kinds of things. So thinking beyond the normal risks to your, to your jurisdiction and then what you might be able to do to prepare for those, even though you don’t get that normal cycle anymore.
[00:06:41] David Tobias: You’ve told me before that, you know, FEMA would practice these events, right? You would practice for the worst case scenarios and that these scenarios in real life or in practice never happened at a convenient time. They were never 3pm on a Tuesday. Right? If you’re an insurance executive, you’re running a claims team, a cat response team, what do you think you can take from some of those lessons you’ve had? You know, from some of these agencies where you drill, whether it was you know, the fire department, but fema, et cetera, where you drill and you practice like the event is real. What do you think? There’s some takeaways for the insurance industry
[00:07:17] Jeremy Greenberg: here, so a couple I’d offer. One, do the basics brilliantly, right? There’s always this notion that these incidents are so complex that you just don’t know how to start the response. And to me, every disaster, whether it was the most unique disaster I ever responded to. But you go back to the basics, you assess the situation, make a determination on what the resources are and you work your way through a progression of steps to bring stability to that incident. And I think understanding what your plans, policies and procedures say, but understanding from jump, what these things mean and what or what they say and what they mean because to your point, it’s never going to happen in convenient time. The worst disaster responses I’ve, I’ve dealt with always started with a 2am phone call, right? And sure you have a watch team on duty and thankfully that’s the 24 hour cycle, but you’re waking people up mid sleep, go to a checklist and start the process there. And even in the more sort of basic responses that we’ve dealt with, go back to a checklist, never assume that you are smarter than the plan that you wrote. So I think doing the basics for Lambley to don’t be afraid to introduce a ton of stress into an exercise when you do the public private comparison. So the public sector inherently is focused on stabilizing an incident. I’m talking about disaster response, but stabilizing incident and helping the community. The private sector is doing the same, right? It’s particularly an insurance side. It’s about getting their individuals who have coverage paid out to stabilize what’s going on in their homes, in their businesses and then to start to generate that revenue. And I think there’s this, this misconception sometimes where it’s like, oh well, the private sector is only worried about the bottom dollar. I don’t buy into that because the private sector and capitalism is how the nation works, right? If you can bring that community back up on plane, then that’s exactly what we want to see happening. So think about it as more of a partnership, not so much a, a, a fight between public and private. So, so practice often, don’t be afraid to introduce some stress and then this is harder on the private sector side is be open about vulnerabilities, right? If you have a gap in your capability, hey, I can only assess 500 structures, 10,000, whatever that number is right. Make sure that that number is known within your team. Because the worst thing that can happen after a disaster is additional surprise about your capability. You want to know where those gaps are. I’m not saying you have to fill all those gaps and you have to build a plan and go, I got to go fix that right now. But understanding where that gap is in the system I think is probably the last critical point that I would offer on this.
[00:09:50] David Tobias: You’ve mentioned that one disaster can get another and another, right? These things can become linked, right. You have a wildfire that creates a burn location which can then create a mudslide incident, et cetera, et cetera. How should the insurers think, like emergency managers, about how these things might be linked and actually become bigger events than they thought at the outset?
[00:10:13] Jeremy Greenberg: How do you currently assess it? Now everybody looks at risk as vulnerability, consequence, probability, like the formulaic approach. It’s there, the math is there. But it’s how do you account for these recurring disasters? You mentioned it, right? So the wildfire creates burn scar. Burn scar then exposes areas to floods that normally hadn’t had flood. Then they have flood issues. Then unfortunately it’s these same areas that are impacted by drought that creates more fires for the fuels and so on and so forth. So you have this recurring risk calculation, but then you also have areas where you have concurrent disasters. So we saw this is years ago, but there was a wildfire in Hawaii during a hurricane, right? That a wildfire, literally it was brush fire that started, it was fed by hurricane force winds. Unfortunately, all the normal procedures of hey, fly helicopter up, Bambi bucket water down. You can’t do, it’s a hurricane. So I think it’s the broader conversation with the insurance community about how we’re really doing risk calculation. It’s no longer just a geographic vulnerability against one or two threats, it’s more that comprehensive. And Dave, I’ll be honest, I don’t know where the line is between. You described microcaps earlier. You know, what’s the threshold? What is the threshold when the incident is beyond the capacity of a local jurisdiction? If you have these back to back concurrent problems, even the most seasoned disaster organizations and the best response organizations are going to have to throw their hands up and say, hey, I need help.
[00:11:40] David Tobias: When you look at the first 24, 48 hours of these events, what are some tools that you are using to try to sift through the information to get to the reality on the ground? And how could it ensure, you know, take that, take that Forward in the same way FEMA does.
[00:11:55] Jeremy Greenberg: So one is to your point about data saturation, right? Throughout my career I, we started in this. I would describe somewhat data poor environment or maybe less data than we have today, but it was almost a certain outcome. You knew exactly how a storm was going to play, how certain jurisdictions would act and react, how, you know, sort of the societal norms and the disaster would play hand in hand with each other. And isn’t that the. Oh, times were so much easier back in the day day. But they were to a certain extent. You didn’t have a lot of the barriers that we have today to sort of that. That predictable outcome. Now we have all of this data, but it’s unpredictable outcomes. So it’s, it’s almost this flip where it’s like, great, I now have data. And, and you know this really well from where you said, how do I take that data and turn it information into information and when do I turn that information into knowledge? And not in that like buzzwordy way again, I’m like, oh, that’s cool. You just said take data and made it into knowledge. No, really, like how much data is too much data? Then what do I do with it and how do I look at it and then how do I make a good decision around it? So to answer your question, I’ll give you an example. If you look at. And this is something that near map does a great job collecting on and for both public and private. A tornado blows through an area and they unfortunately don’t happen in the middle of the day when everybody’s awake, they’re devastated, they happen at night. It is just bad luck on bad luck on bad luck backed up by science as to why they have in the. But so this tornado blows to an area. The very first question from my old response seat was how bad is bad and what does the infrastructure look like? Is the fire department intact? Is the police department intact? Do they have some command and control structure? Are we able to get in touch with the local emergency manager? So you start to assess that situation with imagery collection, you can get that. I wouldn’t want to say instantaneously. I think that’s overselling, but. But darn close, right? It is. As quickly as an aircraft can get up, a drone can get into position, in some cases satellite overhead, whatever it is, and you can start doing that assessment. It’s the same things I used to want to know on the response side. The same things insurance folks want to know. How bad is it? How accessible is it? Right. If it’s an isolated area where there were. This one part of the state was only accessible by two bridges and both those bridges were out. And does it look like people are going to be able to stay where they are or do you need to evacuate them in? You know, is it a proximal evacuation, hey, just from one side of the river to the other, or is this like a significant movement? And all of those things, all the nothings, all of those decisions are being informed by this better data collection because it’s. And I’ll wrap it up here, but it’s this push and pull. So if, if I get a notification that there’s an incident in a particular area, there’s a tornado, you’re going to start pushing resources towards them. But you want to create an environment where the local responders are able to pull down, you know, what they need. And that really becomes a much better orchestrated activity when you’ve got great situational awareness. So I think early collection, quick collection helps inform resource allocation. So I think back to the beginning of making sure you have a good flick as to what, what your problem sets are and that can help you make better prioritized decisions.
[00:15:12] David Tobias: Yeah, you said something I thought was really insightful. Maybe these days it’s not so much being data for maybe, you know, there’s more data flowing in, but that knowledge, that gap from data to knowledge still exists, I think. Right, because. And as you add more data to it and you add more events to this equation, getting to that knowledge and getting that reality on the ground becomes harder in certain regards because there’s more information flowing than there’s ever been. If you look back, you know, a few years now, obviously technology has advanced quite a bit. And what we can do with LLMs and otherwise, what technology do you wish that you had back when you were sitting in that seat that we have today, that if you, if you had back then you think would have been a superpower?
[00:15:55] Jeremy Greenberg: I think the really dialing in on that, on the imagery collection is something that we started, started to do my last couple of years that I was there. So I’ll talk about two things. So one is the imagery collection and really being able to leverage both the collection side. But moreover, the AI generated analysis to be able to say, and FEMA and the entire federal interagency in many states have great geospatial capability, but they were spending time, once the collection was done with humans looking at, you know, the images themselves, the obliques and all the way down of like, is this damaged? Is it destroyed? Is it moderate, you know, and leveling the assessment? And now, you know, I’ve seen some of the things you guys have posted on LinkedIn, put out, you know, in different disaster states. That’s happening again almost instantaneously and it’s not taking the place of the responder, but better informing Back from it was data, now it’s information. Now I know not just a tornado went through a geographic area from point A to point B, but I know roughly how long it was on the ground and I can assess where, what the status is of these homes. A wildfire that is in a remote location that you can’t access necessarily by ground or you wouldn’t anyway. You can now paint that picture much clearer of how bad is bad and is it getting worse or getting better? Back to before, about what decisions do you want to know? It’s much more helpful to know not just the status of our problem, but is it trending up or trending down? Because something that’s sort of green is good for now, but trending down is, is going to get my attention more than something that’s red but trending up. Right. The whole idea behind disaster relief and SAS management is you want to prevent it from getting worse. So I think one, the imagery collection side two is the, the overall data analysis. If you’ve ever been in the National Response Coordination center or any emergency operations center anywhere really in the world, they all, they look and feel roughly the same, different scale. But the idea is I’ve got screens everywhere. Somebody would walk in, you just stare at a board and you’re like, oh, that’s super cool. You can point to it and yes ma’, am, yes sir. Like super great stuff. This is really good. And people nod and they move along. But now how do you really leverage that digital real estate? How do you say, hey, this board that my situational awareness chief stares at every day, or this one that the log chief stares at every day, that’s the most important thing that’s in their line of sight. So how do you use the technology to like. One of the simple things that our geospatial team did was they changed the underlying map, the default map, to not just be a default ARCGIS or ESME map, but a data informed map. So if you are, if your board was about health and human services, it would be where there are medical deserts in the United States. If it was a water wastewater treatment facility board, where are these treatment plants around the United States? So you’re giving more and more context around what you’re staring at. So it’s no longer just a board that super looks or looks super cool, but one that I can look at in a glance and sort of know what’s going on very quickly.
[00:18:55] David Tobias: Yeah. And I think, you know, LLMs can, can help sift through some of this and at least suggest, you know, where to spend your attention. Now needs oversight. And I want to get to that in a little bit here. But, you know, you can’t take these things blindly. Right. You need to have that human intuition, that human intelligence as part of the decision making process. But I think the other thing I’ve seen change is how the technology is allowing a feed of events. So, you know, I think about the Palisades fire, there’s Spokane fires that just happened. Milton, Helene, you know, these events are dynamic, so they’re shifting. And so because you can now analyze some of this data more quickly, you know, you know, keep it to aerial imagery just for the sake of argument here. But, you know, as the wildfire changes, you can change with it. You can run the AI to say, okay, this area was safe, but now it’s damaged as the, as the wildfire horizons moved. It’s not event happens, event done. Right. It’s, it’s an ongoing process.
[00:19:56] Jeremy Greenberg: Now I think related to that is all of those things are true without losing public trust. Right. So if you were using wildfires as an example, that is one of the most difficult decisions I’ve ever seen. I’ve never made an evacuation decision about a wildfire personally, but supported many jurisdictions who have done that, such a difficult thing because they are moving very quickly, the winds are changing, the fire line is like everything in that is dynamic and people are resistant to evacuation. It just humanity. You don’t want to leave your things behind. If you or I were told to evacuate today, there had to be a very good reason why. And I’d have to believe and have trust in someone. And part of that challenge, and we saw this in the last several years of fires, is particularly in areas that were not prone to it before. Back to the very beginning of our conversation. If you’re not used to it, you’re not trained to it, you’re not attuned to it. You have to make the decision based on the information they provide at a moment in time. And if it changes again, human nature, hey, you told me I was safe here. Now you’re telling me I’m not. Or the hurricane flaw that we’ve seen many, many a time, hey, the forecast was in one area. They were told to evacuate. And then the very next year they said, oh, I don’t need to evacuate. This happens every year. And that’s where you see a lot of the freshwater drowning through surge and those kinds of things. So it’s all the things. Understanding the dynamic nature of the incident itself as the variables change, but also keeping that trust in place for both the public that you’re warning and the insurance company behind of, here’s what we’re able to do to get you covered. I trust it to go do this. I’m going to try it today and see where that trust factor is.
[00:21:35] David Tobias: There’s so many similarities between what FEMA and some of the emergency response, you know, whether the state and local is trying to do in the insurance industry. But that connection, that public private connection, you know, it’s there, but could be stronger. What are some suggested suggestions you might have to the industry to help, you know, bridge that gap a little bit?
[00:21:56] Jeremy Greenberg: A couple areas that I think the insurance industry can focus on. One is you mentioned earlier that insurance companies are designed to make people whole, bring them back up online and almost to a T. FEMA through individual assistance says, hey, we’re not designed to make you whole. Right. It’s this part. So it’s, it’s understanding the entire part of the, of the pie. There’s so much more between other federal departments and agencies that can offer individual assistance and small business and private insurance. Like it’s this, it’s this pull altogether. So I think one, being open about what the role is of insurance. It’s not an organization that you pay every month and they take your money away. Like that’s, it’s, there’s this, I see it, I don’t subscribe to it, but I see it where it’s people, oh well, I’ll never need anything. And if I need a payout, they’re never going to be anyway. That’s not true. Right. Insurance companies worldwide do phenomenal work in, in paying out claims for people that are unfortunately impacted by, in this case, disaster. So one, being forthright about what the insurance industry really is and what it’s designed to do. Two, and I would say this just as a homeowner and a responder is lower the barrier of access to the extent that you can use plain English terms, right. And this is a problem in the emergency management community. We use jargon all the time and lingos and acronyms. People don’t understand it. So the insurance company, to the extent that you can break it down, explain what coverage is or what the variables are in the coverage, what the premium actually covers, what the expectations are for deductibles, all of the things that homeowners need to know. Because back to our very beginning, when you’re in panic mode, you’re in fight or flight, you’re not gonna be able to process much, right? Your brain capacity actually reduces. We know this because you’re panicking. So make it as simple as someone can, as simple as it can be. It’s not that people are dumb. You’re just panicked and stressed and you just want to make a good decision. So I think part one is keeping it as basic as it can be. Two, on the public private partnership. I encourage every insurance owner, operator, provider, underwriter. If you don’t know your local emergency manager in the community in which you primarily insure, go find them. And if you need help, reach out. I will happily connect people. Because there’s this I hate the old adage of you don’t exchange business cards that are disaster. Because you do all the time. You’re like, hey, here’s my number. But getting to know people beforehand. So when the response comes into play and someone from Pick an insurance company shows up, they’re not excluded from the discussion, but they’re in the room where it happens, right? They get brought into the discussions about, hey, we’re going to go do damage assessments or you guys are going to go fly. And that imagery will be available for the public side and the private side. Inspectors are going to go out, you’re going to target this community, you’re going to set up a disaster recovery center and you want the insurance company with you. So really getting into that, into that cycle, optimally, where you’re exercising together, but at a minimum, hey, I know Dave. I’ll call him and he’ll be the guy who comes or he sends somebody else and it’s a trusted relationship. I think that that’s part two and then part three, and we talked about this earlier, but just to double click on it is to say, hey, from a business perspective, make sure the insurance companies have a business continuity plan that they know how they can operate if they’re impacted. What does it look like if there’s a natural disaster and an adversarial cyber attack at the same time and you can’t get to the systems that you normally operate off of, or what happens if, you know, just dumb luck, the disaster itself happens to impact you in your office. What do you do with your personnel? What do you do with your adjusters? How do you Care of the families of all your employees. So all that say, don’t think that you’re impervious to the disaster itself because it’s going to happen. It happens. Happened to me when I was at FEMA in the field and at headquarters. Just have a good plan to take care of your team and then be able to execute your mission.
[00:25:46] David Tobias: Human element here is so important. And you know, I’ve often heard you talk about this human side of recovery.
[00:25:53] Jeremy Greenberg: It’s.
[00:25:53] David Tobias: It could be, you know, disaster had happened or wildfire, a flood, et cetera. It’s. It could be this person’s worst day or one of their worst days of their life. Life. Right. This horrible thing has happened. They don’t know what to do necessarily or how they’re going to, you know, recover from this. They don’t want another form. They don’t want another, you know, you know, document to fill out. How can property intelligence help improve that experience for somebody on the ground tactically?
[00:26:20] Jeremy Greenberg: I’ll combine it property intelligence with some of the things that we’ve already talked about is if the responder, right. And I’m saying that very globally, it’s the firefighter, the police officer, the EMT and then it’s the emergency manager and then it’s the insurance company. If the, the community that is coming to help the person in need can be best informed, then you’re already reducing the burden on the survivor. Right. It’s. It’s. Think about it. This is a great analogy, but think about when you go into a doctor’s office and they ask you a bunch of questions and you have this reaction of like, don’t you know that already? Is it in your system? Why are you asking me these questions? They’re asking for very good reason. They want updates. But think about from the response perspective, if the team that’s going to interact with the survivor has. And this is. This is not Pollyanna, like this is happening now, but has both the property intelligence about. And we’re talking homeowners, not commercial right now, but just like if just homeowners policy have information or the person that’s coming with me has the information about their home, their policies, previous loss, anything that can help make that discussion a little bit easier. And I get it, there’s tons of fraud and we have to be careful about how we’re approaching these things. But I think if we can increase the amount of information that we’re walking in with to help survivor, that one is going to make their bad experience a little bit easier. Two, this Gets back to the relationship side of this normal. It’s almost like a conveyor belt process where a survivor has an incident, happens to them, then they get visited by a FEMA person or local responder to hopefully sign them up for individual assistance. Then the insurance person has to come out, then they’ve got to file and there’s no way of getting around that. It has to be a sick punch away, one, by law. But two, it’s just the way the process works. But if you can make that conveyor belt process a little bit more human. And again, back to the cognitive offloading to a certain extent, if you can, let the system do some analysis in the background and we as humans can spend more time interacting. I mean, we’re in different locations right now, but having a great conversation. So is there a way that you can empower the responder, the insurer, insurance company, the agent, to be well informed and be able to do that intake? I think that the unfortunate incidents that are going to happen will be a little bit easier. That’s one side of it. The other side is on the risk calculation. We’ve talked a lot today about how do you assess risk, how do you calculate risk? I think that the overall property intelligence, both on the commercial side and the homeowner side, really even more so on the commercial side. Talking about risk and understanding what mitigation actions can be taken. Persistent imagery, right? You’re flying every year or every six months. We’re starting to see dynamic changes in environments because of these weather patterns we’ve talked about, or construction or, you know, the strangest thing happened.
[00:29:14] David Tobias: Cool.
[00:29:15] Jeremy Greenberg: Well, we collected that on imagery and I now know that I’ve got a problem over here. Or you know the question I used to ask every time there’s an incident, hey, what did it look like yesterday? Somebody’s like, oh, the water purification plant was down. Okay. Oh, it’s been down for like a month. They’ve been using a temporary one. You’re like, great. This gets back to the property intelligence side of like, what did it look like yesterday to paint a better picture so I can think about how I respond and stabilize. So two sides of that coin. But I think both are equally important.
[00:29:42] David Tobias: If you were going to leave an insurance executive with one thing, one takeaway here today, you know, it could be technology, could be process, but you know that you’ve learned in your disaster response days that you think they could take back to their teams and run at what would it be?
[00:29:58] Jeremy Greenberg: One, I think it’s understand how your systems are built and where your information comes from, that’s critical. Two, always the old adage, if I know something, who else needs to know? So how does your information flow around your organization? Where does it come from, where does it go and what do you do with it? And then three, and it goes back to partnerships. It is, you know, spend as much time as you possibly can building a network of trust in the communities that you service.
[00:30:22] David Tobias: Well, I just wanted to thank you today for joining the Reality Layer podcast. Obviously, you’ve dealt with the reality of many of these events in your various positions over the years and tons of experience reacting, using data, trying to figure out what is actionable out of that data. So I really appreciate you sharing your thoughts here today, Dave.
[00:30:40] Jeremy Greenberg: It’s been great being on. I appreciate it and thanks for all that you and the Near Map team do.
Meet the Host
Dave Tobias
Dave is Chief Product Officer at Nearmap, where he leads product strategy across the property intelligence portfolio. He co-founded Betterview, the application now used by carriers across the US for underwriting and risk selection, and joined Nearmap through its acquisition in December 2023. He has spent more than a decade building the tools insurers use to understand property risk.
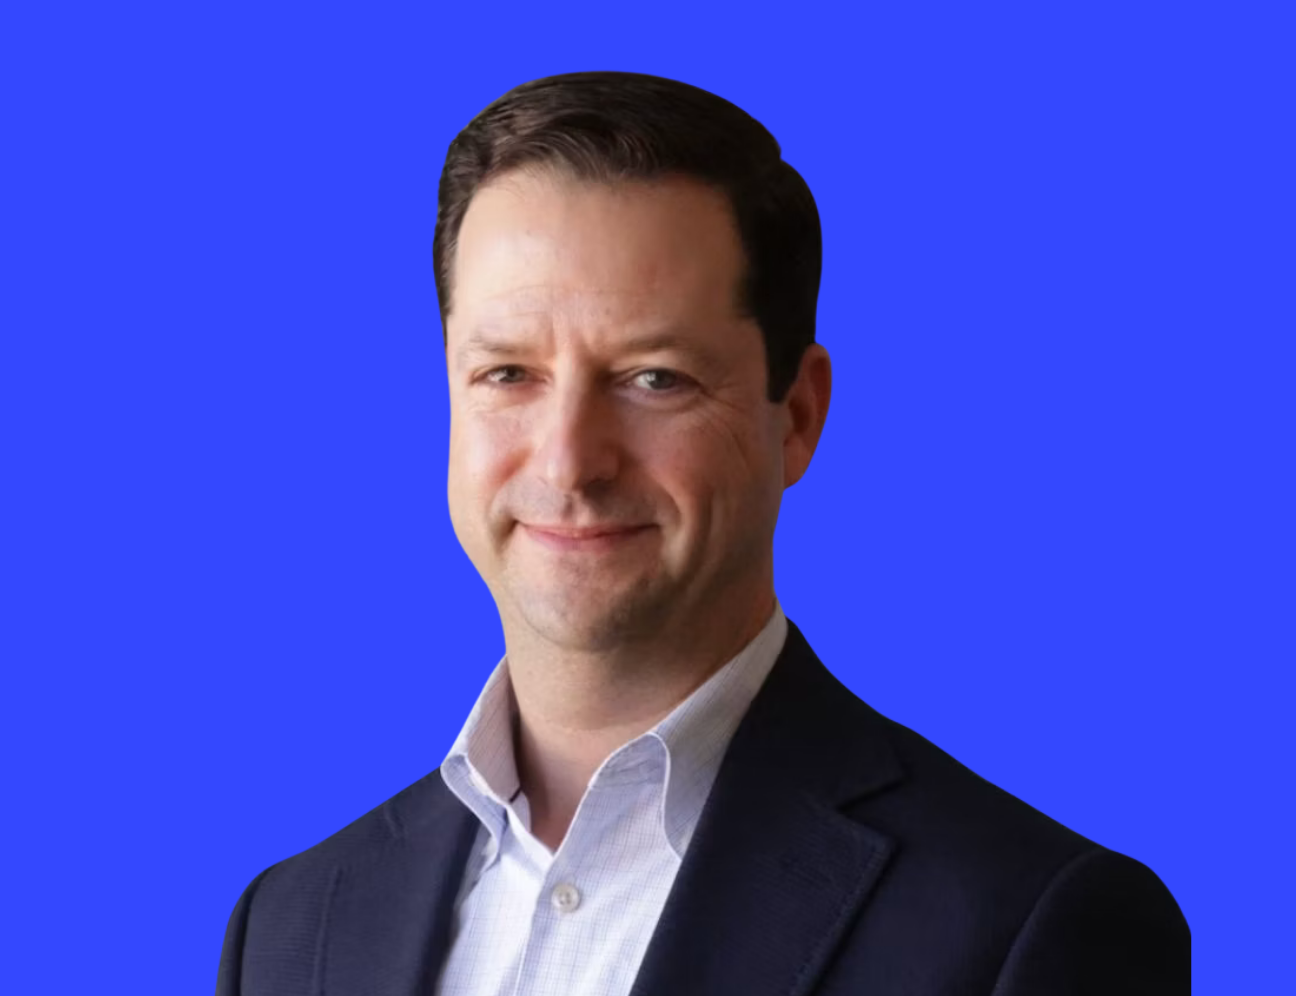
Meet the Guest
Jeremy Greenberg
Jeremy Greenberg is the President of Provincial Strategies LLC, an emergency and risk management consulting firm. He is also Senior Advisor to Aspen Digital, a program of the Aspen Institute, and an Adjunct Instructor for the University of Chicago’s Threat and Risk Management Program. Jeremy brings more than 23 years of federal service to his work, including five years as a member of the Senior Executive Service. Throughout his career, he has held key positions across both the executive and legislative branches.
See the Reality Layer
Every episode covers claims, catastrophe response, and the AI reshaping insurance technology.
View more episodesExplore the latest
Nearmap Labs
Explore the research and early-stage technology behind what's next in property intelligence. Get hands-on with new tools before general release, and meet the people building them.
Explore Nearmap Labs
Customer Stories
See how carriers put property intelligence to work across underwriting, renewals, claims, and catastrophe response, and what changed once they did.
Read Customer Stories
Webinars
Go deeper on the topics the show covers. Sessions with the practitioners and product teams closest to the work, available on demand.
View Webinars